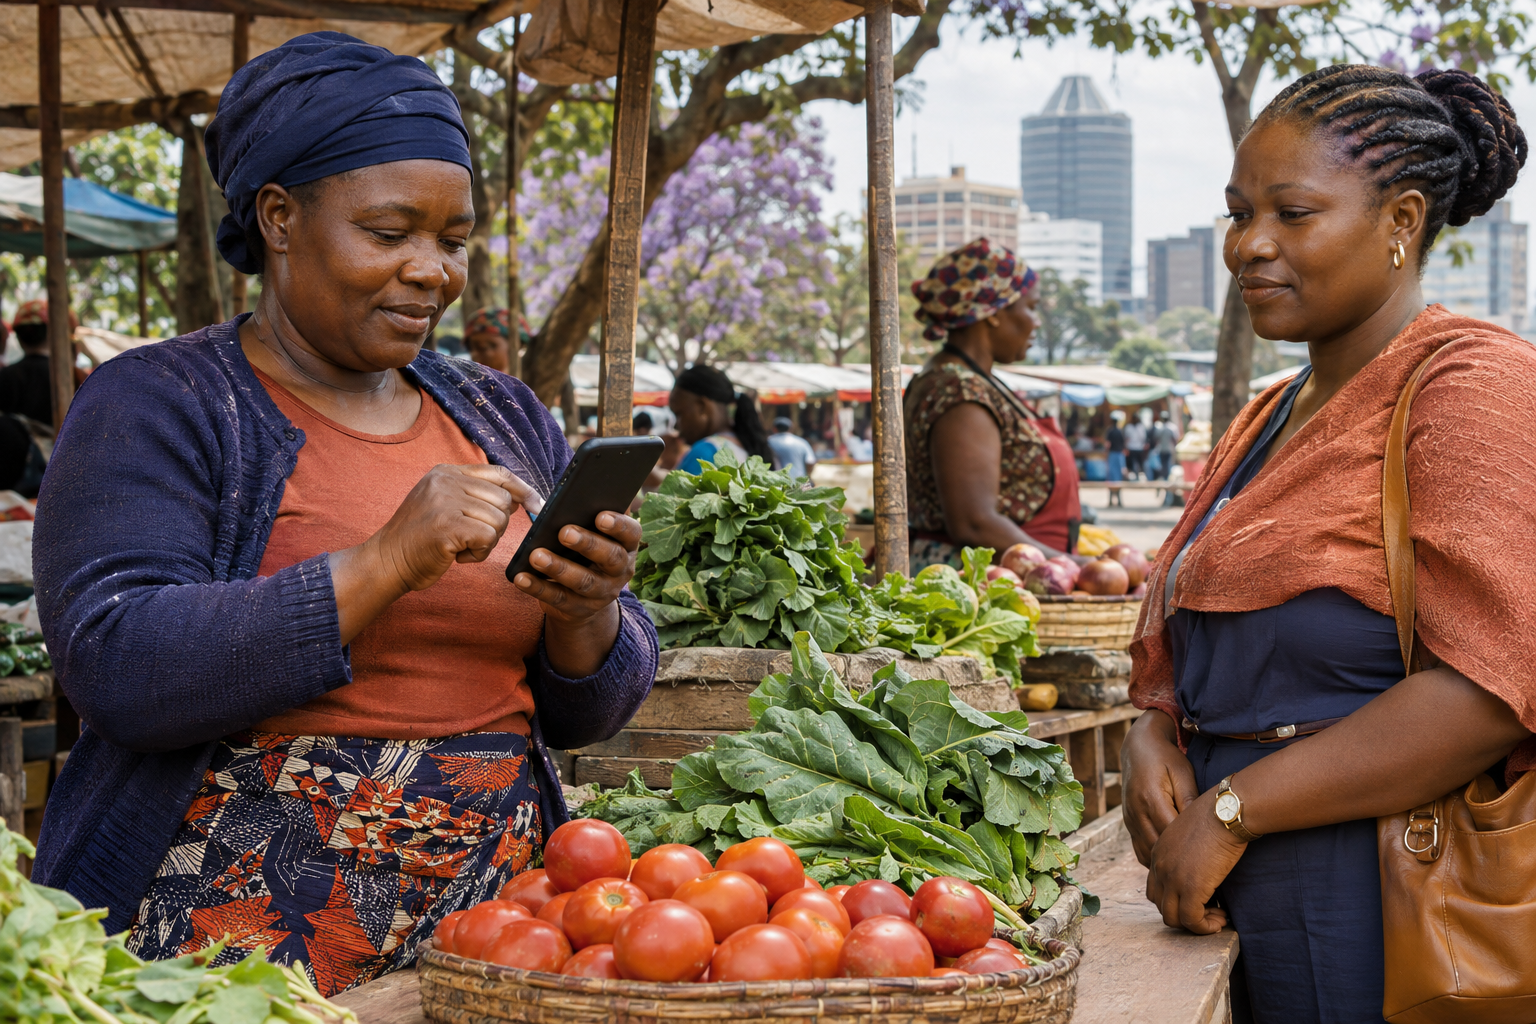
Most small traders in Zimbabwe run businesses that are profitable, cash-based and invisible to a traditional credit officer. They have no audited accounts and often no payslip. Yet many of them move money through mobile wallets every day.
Banks and fintech companies are now trying to turn that transaction history into credit decisions. If they succeed, millions of people could access working capital for the first time.
Partnerships, not competition
Imba Capital Bank and the startup Nyanga Digital announced a partnership this year in which Nyanga provides the customer relationship and data, and the bank provides the lending balance sheet.
The Leader Intelligence Briefings for Executive Teams
Learn about corporate briefings“The bank has the capital and the licence. The startup has the trust of the trader. Neither can do it alone.”
— Farai Dube, CEO, Nyanga Digital
The hard parts
- Data quality: transaction data can be patchy when customers use several wallets.
- Consent and privacy: lenders must meet data protection obligations when they use personal data.
- Responsible lending: small, fast loans can create debt spirals if poorly designed.
Executives interviewed say the winners will be those who treat credit scoring as a relationship built over time, not a one-off algorithm.
Where this leads
Executive analysis for decision-makers and capital allocators.
- Opportunity
- Data, risk and product roles in banks and fintechs. Partnerships between lenders and platforms that hold customer relationships.
- Risk
- Over-indebtedness, data protection obligations and default rates in a downturn.
- What to watch
- Bank and fintech partnerships, and regulatory guidance on digital lending.