You came back to Zimbabwe after more than a decade abroad. What made you return?
I wanted to do the work where it matters most. In Johannesburg and Nairobi I saw what well-designed finance can do for a small business. I kept thinking about the traders I grew up around in Chitungwiza, and how little the banks offered them.
Imba Capital was a corporate bank for most of its history. How hard has the shift been?
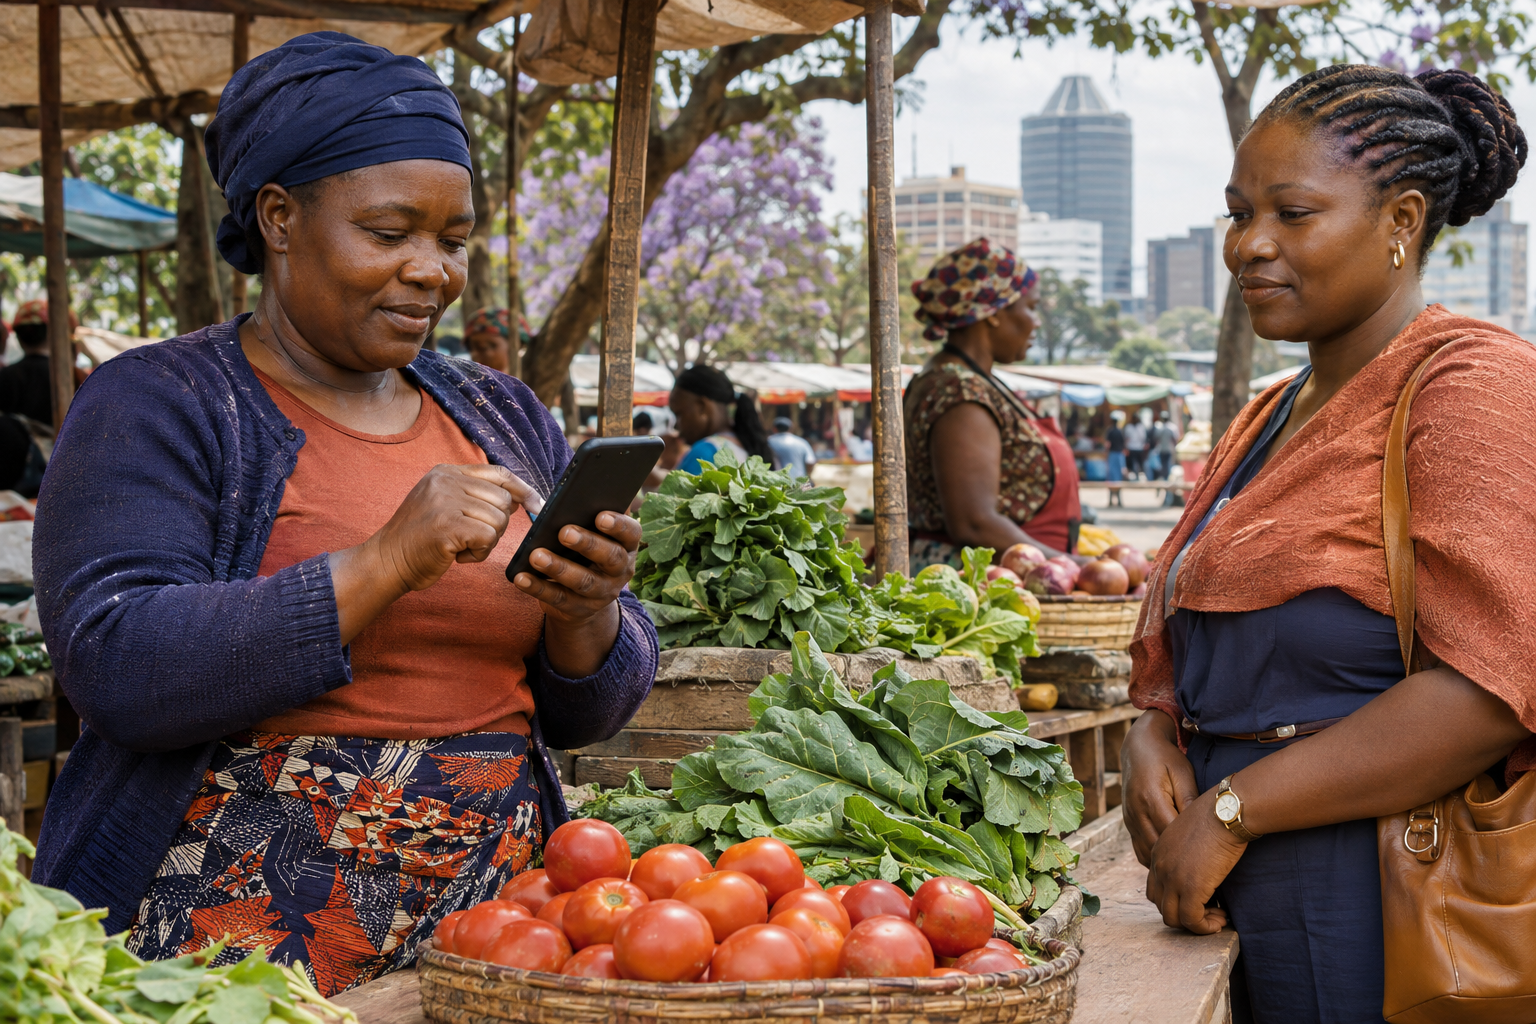
Harder culturally than technically. A corporate bank is built to say no carefully. Serving small businesses means learning to say yes carefully. Our credit people had to learn to read a different kind of evidence: payment histories, savings behaviour, how a customer treats a small loan before they get a bigger one.
“The trader in the market has been running a profitable business for twenty years. We were the ones who could not see it.”
Why partner with a startup like Nyanga Digital rather than build the product yourselves?
Because trust is earned in places we are not. Nyanga's team spends time in markets. Traders use their app every day to keep records. We bring the licence, the balance sheet and risk management. It is a better division of labour than either of us trying to do everything.
Digital lending has a mixed reputation across the continent. How do you avoid the problems seen elsewhere?
Start small, price honestly and never lend more than the customer can repay from their business. We also take data protection very seriously. Customers need to know what we use, why, and that they can say no. If we get that wrong, we lose the trust that makes the whole model work.
The Leader Intelligence Briefings for Executive Teams
Learn about corporate briefingsOn leadership
What have you learned about leading a large, established institution through change?
People do not resist change. They resist being surprised. I spend a lot of my time explaining why, not just what. And I try to promote people who have made the new model work, so everyone can see that it is rewarded.
What would you say to a young Zimbabwean who wants to lead a bank one day?
Learn the numbers deeply, then spend time with customers. The spreadsheet tells you what happened. The customer tells you what will happen next.
“People do not resist change. They resist being surprised.”
Where do you want the bank to be in five years?
I want a market trader in Gweru to think of us as her bank, not a bank for other people. If we achieve that, the numbers will follow.
Where this leads
Executive analysis for decision-makers and capital allocators.
- Opportunity
- Agency banking partnerships for retailers, and product, data and risk careers in digital finance.
- Risk
- Responsible lending and data protection as digital credit scales.
- What to watch
- The results of the bank's partnership with Nyanga Digital over the next year.